

Weekly Market Insights, Friday Oct 16, 2026
Kenya T-Bill Demand Surges to 245% as CBK Holds Rate at 8.75%; Bond Turnover Drops 23%.
Market Overview
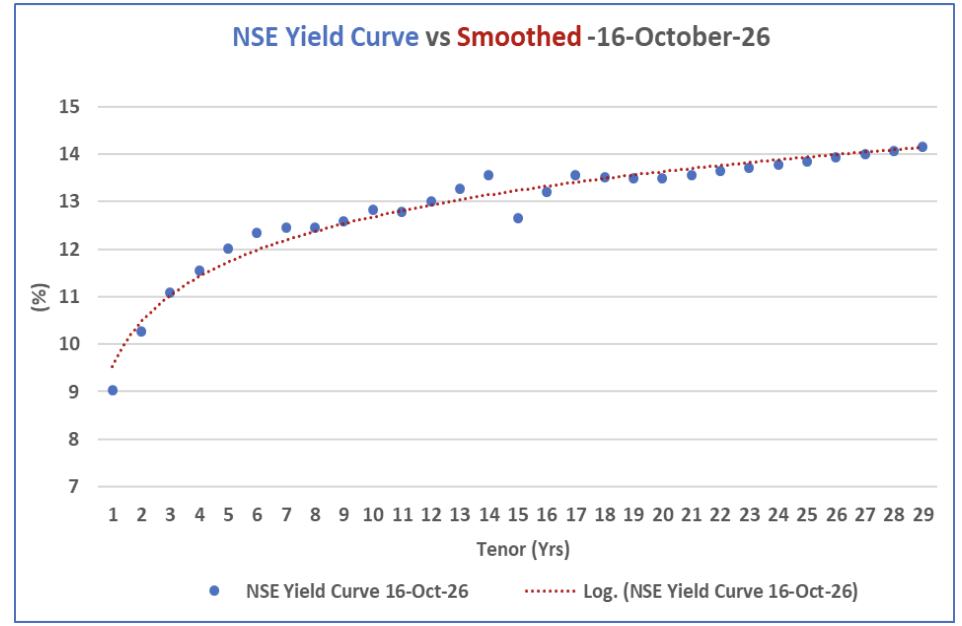
NSE Yield Curve vs Smooth-16-October-26
Week 42 (ended Friday 16th October 2026) of the year showed quite robust performance in the bond market and relatively stable in the equities, derivatives and the international market.
The Kenyan inflation marginally edged upwards in the month of September to 6.8% compared to 6.6% in the month of August.
The Monetary Policy Committee maintained the Central Bank Rates (CBR) for the forth consecutive time at 8.75% in their recent meeting held on Tuesday, 7 th October 2026. • Bond turnover in the domestic secondary market declined compared to the previous week, by 22.60% closing at 40.60 Billion.
Murban crude oil prices increased to USD 102.39 per barrel on October 16, from USD 101.67 per barrel on October 8, reflecting heightened supply risk concerns amid ongoing geopolitical tensions in the Middle East
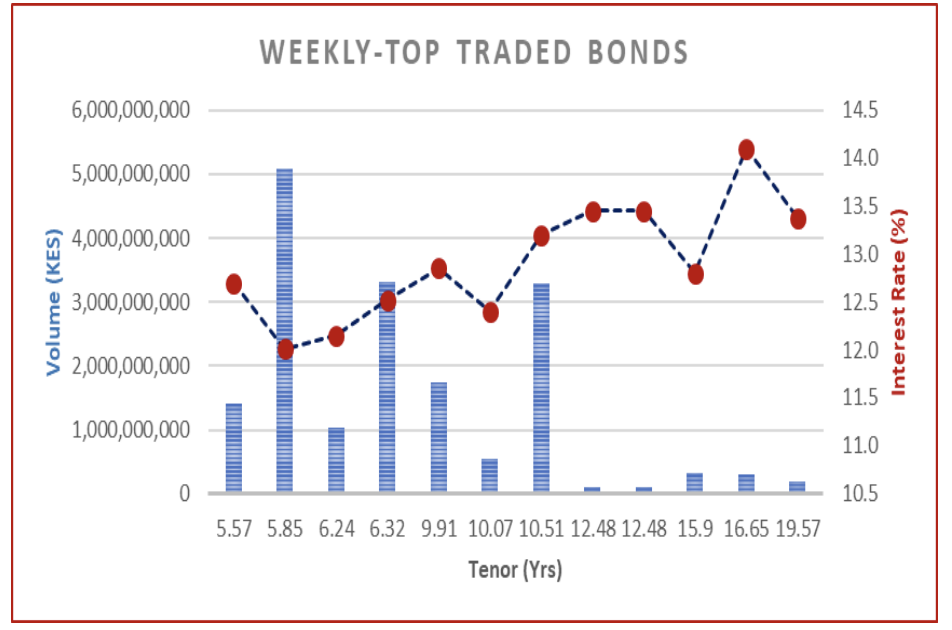
Graph of weekly-top traded bonds
Spot gold prices rose to USD 4,170.25 per ounce from USD 4,133.93 per ounce, as investors increased allocations to safe-haven assets in response to elevated geopolitical and market uncertainty.
In the international Bond market, yields on Kenya’s Eurobonds decreased over the week by 5.80 basis points on average. The Eurobonds performance experienced mixed reaction in most African countries.
The NSE yield curve remains elevated in the short term for the papers below 7 years, with mixed up and down reactions in the medium term 8 to 17 years and elevates in the long term end.
The Kenya Shilling remained stable against major international and regional currencies during the week ending October 16, 2026. It exchanged at KES 129.79 against the U.S. dollar on average over the past week, edging downwards compared to the previous week.
Interest Rate Outlook
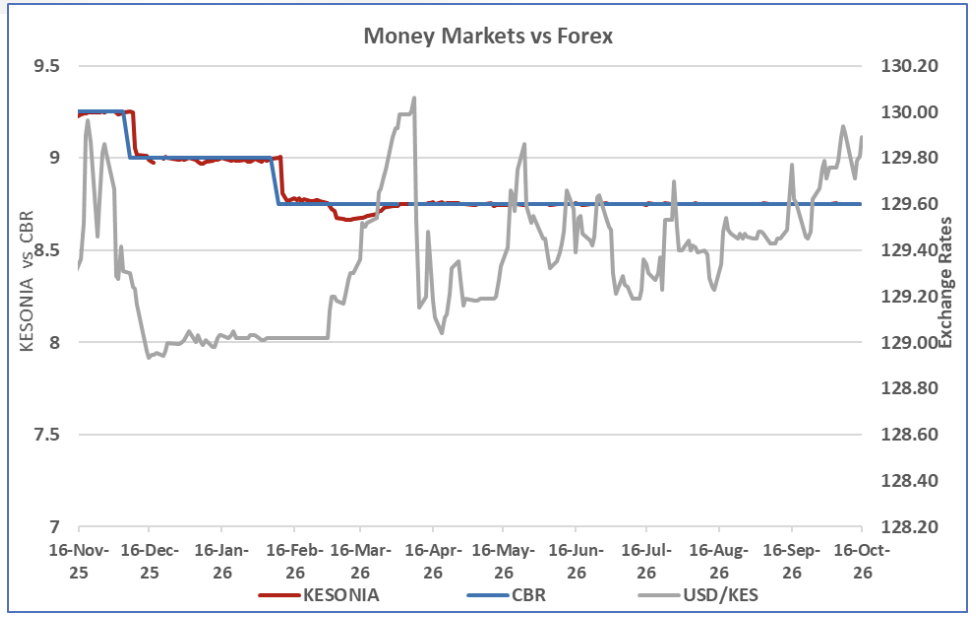
Graph of Money Markets vs Forex
Money Market Trends
The Kenya Shilling remained stable against major international currencies for the past weeks amidst the wars, with no aggressive fluctuations, most specifically against the US dollar.
On average the Kenyan Currency against the USD exchanged at KES 129.79 over the week.
KESONIA rate remained unchanged at 8.75% on average over the week ending 16th October 2026.
This week the Monetary Policy Committee maintained the CBR rates at 8.75 % for a forth consecutive series.
The money market remained liquid during the week ending 16th October 2026 with open market operations remaining active.
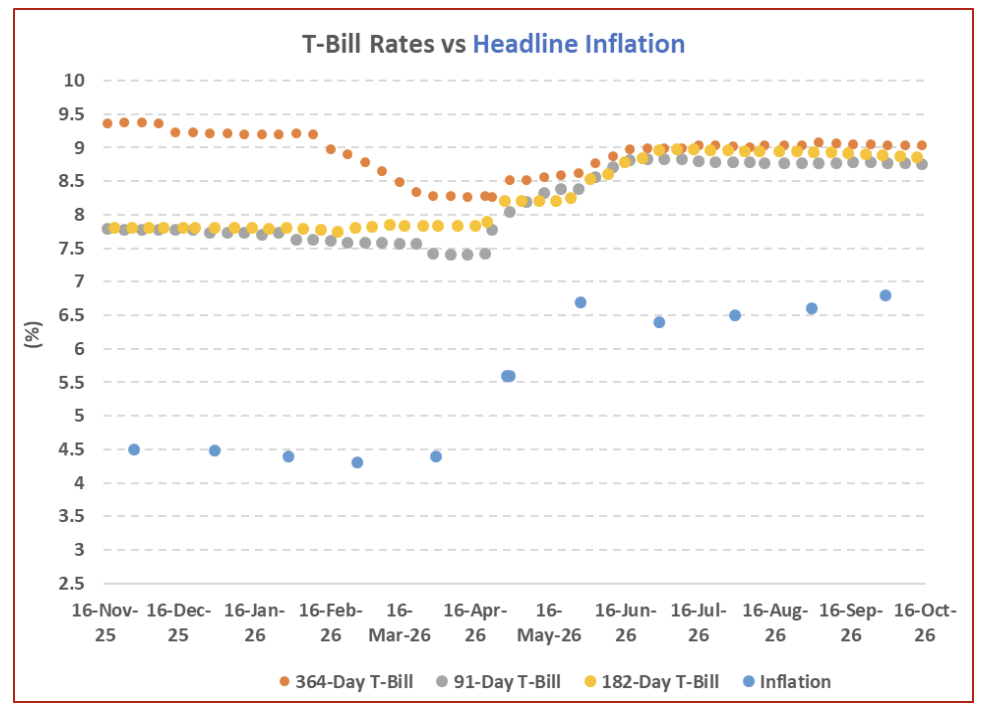
T-Bill Rates vs Headline Inflation
Short End of the Yield Curve and Inflation Trends
The Kenyan inflation marginally edged upwards in the month of September to 6.8% compared to 6.6% in August.
This week, T-bills were oversubscribed for the eleventh consecutive week, with the overall subscription rate coming in at 244.6% lower than the subscription rate of 269.2% recorded the previous week.
The shorter 91-day paper persisted, with the paper receiving bids worth Kshs 49.7 bn against the offered Kshs 8.0 bn, translating to a subscription rate of 622.5% significantly higher than the subscription rate of 627.6%, recorded the previous week.
The subscription rate for the 182-day paper decreased to 120.6% from 155.3% recorded the previous week, while that of the 364-day paper decreased to 66.4% from 96.4% recorded the previous week.
The government accepted a total of Kshs 52.3 bn worth of bids out of Kshs 68.5 bn bids received, translating to an acceptance rate of 76.4%.
KENYA SECONDARY BOND MARKET TRENDS
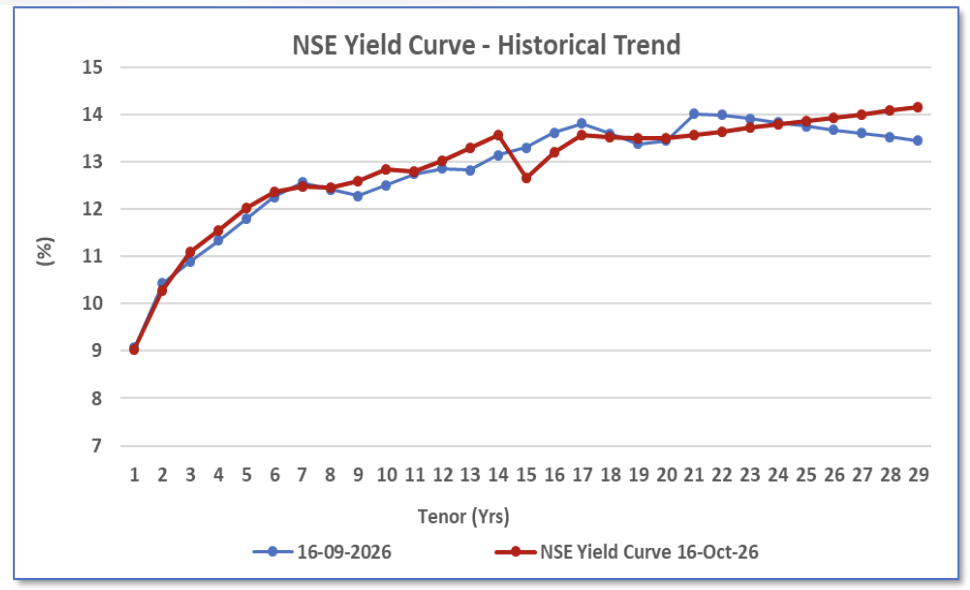
NSE Yield Curve - Historical Trend
The NSE yield curve remains elevated in the short term for the papers below 7 years, with mixed up and down reactions in the medium term 8 to 17 years and elevates in the long term end.
The curves shows extreme performance before and after the CBR rate was maintained for the forth consecutive time and the inflation rise in August and September.
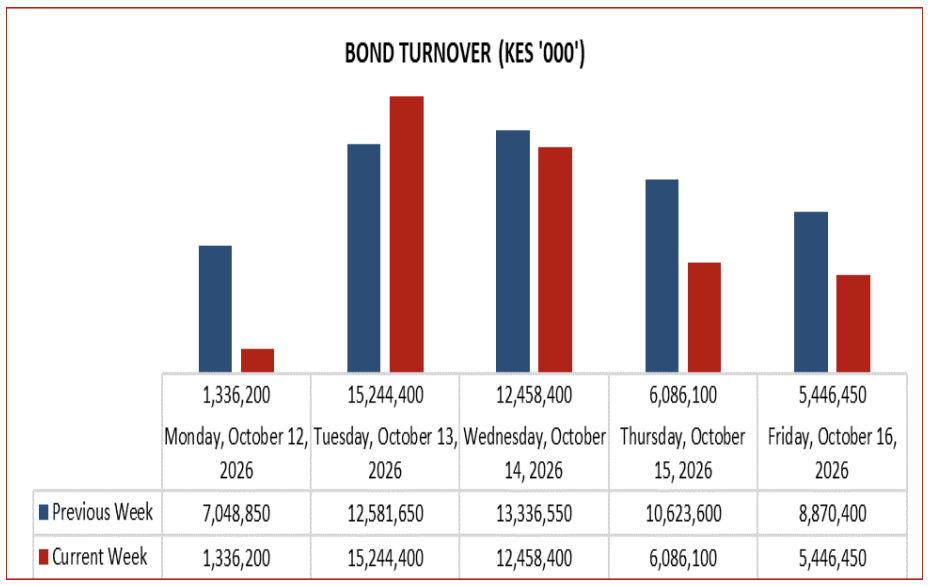
Bond turnover
Week-on-week traded volumes shows robust performance across the two week period with turnover shifting within the week.
The turnover edged downwards over the week with a margin of 22.60% for the week ended 16th October 2026 compared to the previous week.
The turnover closed at 40 Billion down from 52 Billion in the previous week.
KENYA PRIMARY BOND MARKET
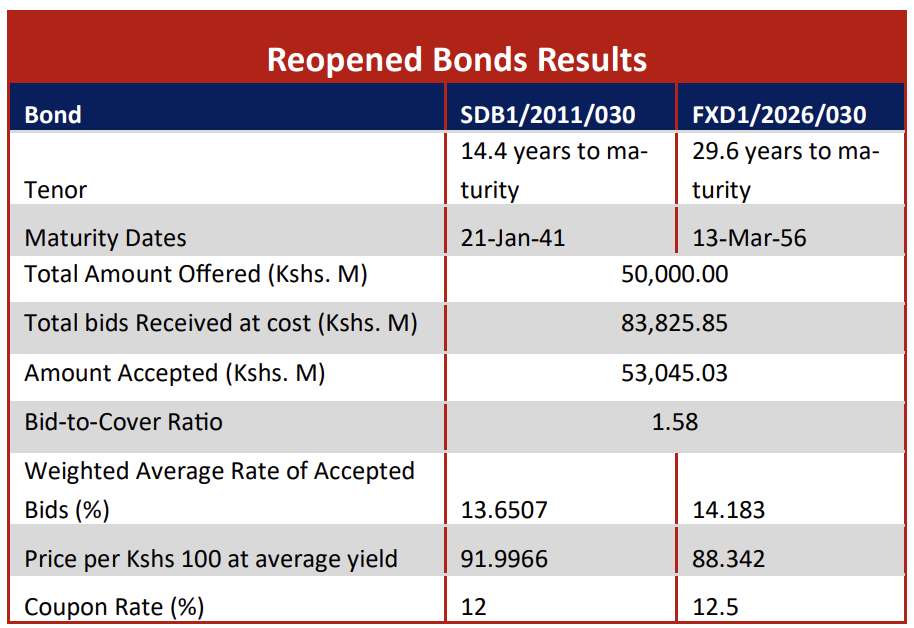
Treasury Bond Auction
During the week, the Central Bank of Kenya released the auction results for the re-opened treasury bonds SDB1/2011/030 and FXD1/2026/030 with tenors to maturities of 14.4 years and 29.6 years respectively and fixed coupon rates of 12.0% and 12.5% respectively.
The bonds were oversubscribed, with the overall subscription rate coming in at 167.7%, receiving bids worth Kshs 83.8 bn against the offered Kshs 50.0 bn.
The government accepted bids worth Kshs 53.0 bn, translating to an acceptance rate of 63.3%. The weighted average yield for the accepted bids for the SDB1/2011/030 and FXD1/2026/030 came in at 13.65% and 14.18% respectively.
INTERNATIONAL BOND MARKETS
USA: Treasury yields fluctuated amid inflation concerns while Equities were mixed, with the Dow gaining while the S&P 500 and Nasdaq declined, driven by technology-sector weakness.
UK: Gilt yields eased as investors sought safer assets. Germany: Bund yields declined amid safe-haven demand and concerns over global growth. European equities remained volatile but showed resilience towards the end of the week.
Japan: Government bond yields remained elevated amid inflation s and expectations of further Bank of Japan policy tightening. Equities were sensitive to global market volatility and interest-rate expectations.
China: Government bond yields remained relatively low amid expectations of continued monetary support. Equities weakened, with the Shanghai Composite falling approximately 2.56% over the week.
KENYA EUROBOND MARKET
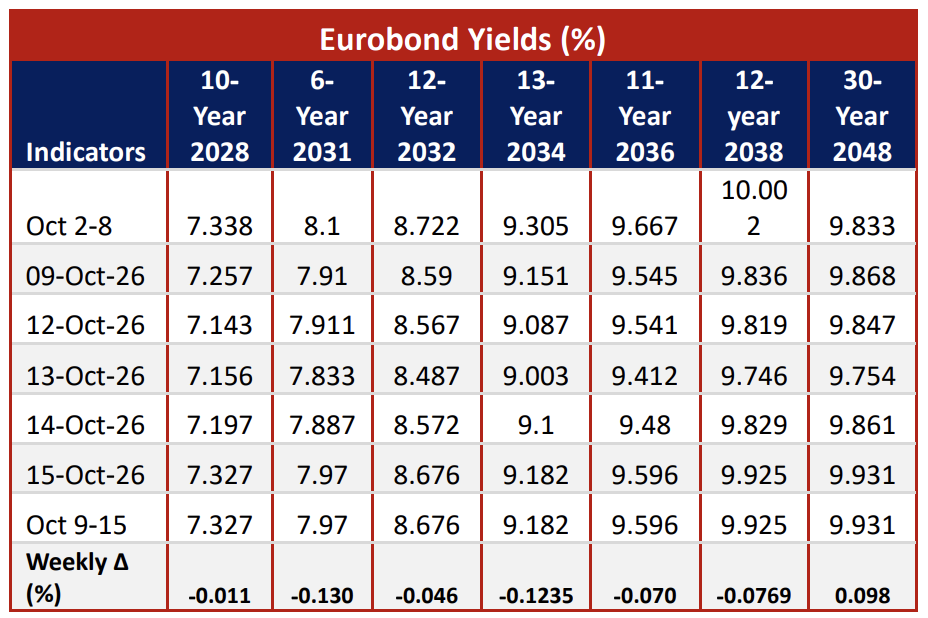
Eurobond Yields
Yields on Kenya’s Eurobonds decreased over the week indicating recovery from the Geopolitical status fires and the global inflation compared to the previous week.
On average, yields grew by 5.80 basis points. This suggests some upward price movement or balanced state by investors in relation to global market conditions amidst geopolitical wars in Iran.
In attachment, is the performance of the Daily Eurobond turnover for the week ended 16th October 2026 in statistical way
BULLETIN BOARD
Equity Market Highlights
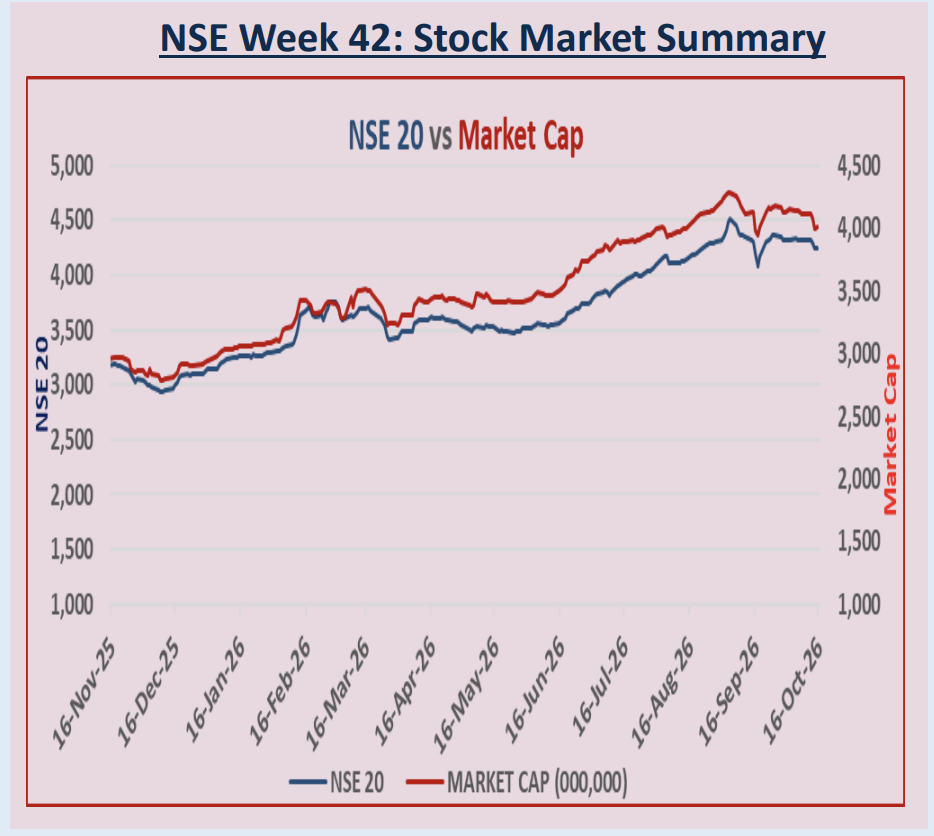
At the Nairobi Securities Exchange, the NASI, NSE 25 and NSE 20 edged downwards by 1.81%, 1.94% and 1.54% respectively during the week ended 16th October 2026.
Market capitalization, decreased by 1.8% closing at 4.036 Trillion.
NASI, NSE 25 and NSE 20 Indexes closed at 240.5, 6828.77 and 4249.24 respectively.
Dangote IPO.
Dangote Petroleum Refinery has extended its IPO subscription period to October 27, 2026, allowing investors more time to participate via Global Depository Receipts (GDRs).
Renaissance Capital Africa is facilitating a public offer for Dangote Refinery Nigeria's IPO Global Depository Receipts (GDRs) in Kenya, targeting KES 39 billion.
Priced at KES 53.50 each, the minimum subscription is set at 10 GDRs. The offer is open until October 27, 2026, with trading on the NSE anticipated to start around December 8, 2026.
Quickmart IPO.
Quickmart’s KSh 15 billion IPO opened on 5 October 2026, offering 2 billion shares at KSh 7.50 each, representing 50% of the supermarket chain’s issued share capital.
The offer closes on 30 October 2026, with listing on the NSE expected on 12 November 2026.
Global Trends.
Inflation concerns remained during the week ending October 16.
The U.S. headline inflation rose to 3.7% in September 2026 from 3.4% in August, driven mainly by higher energy prices.
Core inflation increased to 2.6%, remaining above the 2% Federal Reserve target.
The U.S. Dollar Index weakened by 0.15% during the week.